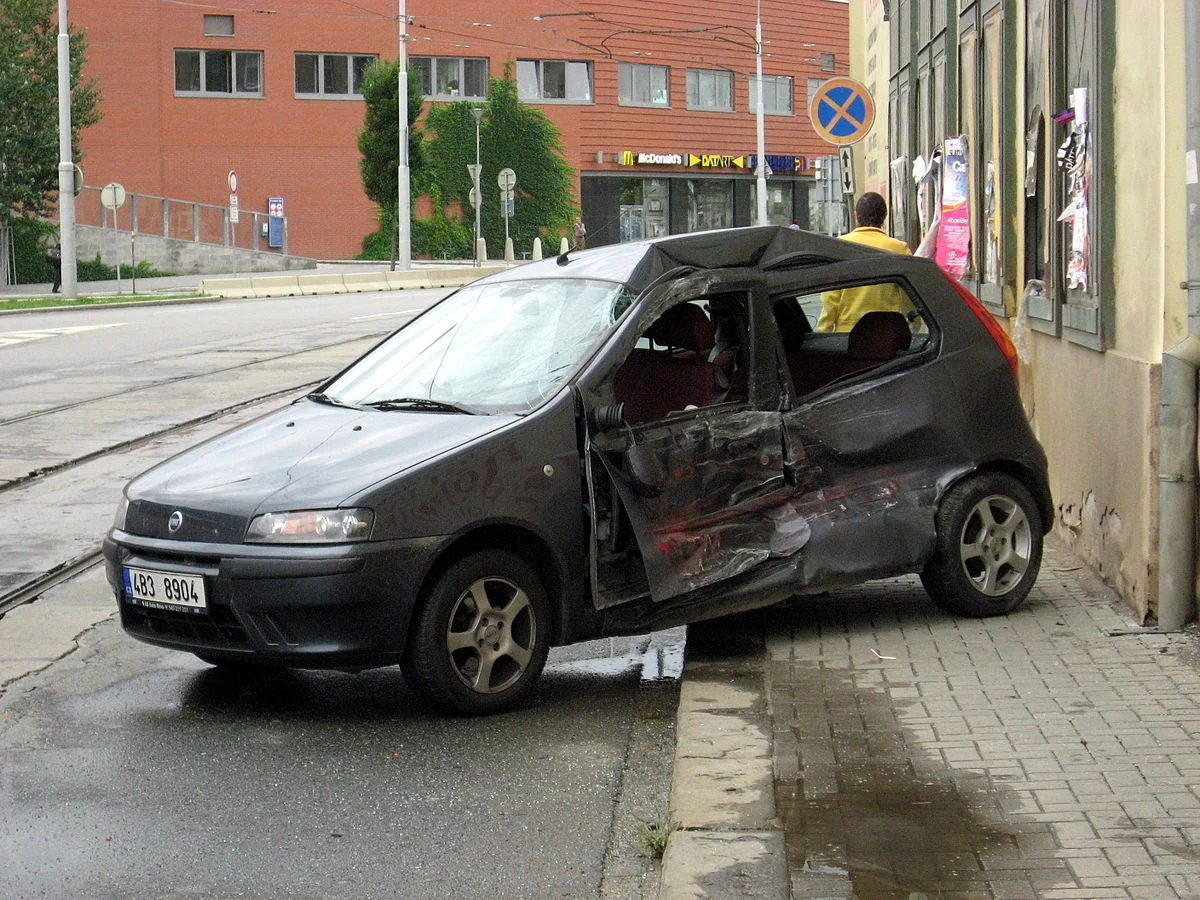
Imagine the scenario: you are driving home after a long day, the weather turns, and in a split-second lapse of judgment, you are involved in a major collision. You are at fault, and the damage to both vehicles—and potentially the infrastructure—is substantial. Without the proper insurance coverage, the financial fallout could be catastrophic, turning a stressful accident into a life-altering debt.
Choosing auto insurance is far more than a mere administrative hurdle or a legal box to tick. It is a fundamental strategic decision that dictates your long-term financial security and daily peace of mind. As vehicle technology advances and the cost of repairs continues to climb, failing to accurately assess your needs can expose you to devastating out-of-pocket expenses or complex, protracted legal battles. This comprehensive guide explores how to navigate the insurance landscape, assess your risks, and secure a policy that truly protects your assets.
The Foundation: Understanding the Three Core Tiers of Coverage
The insurance market is generally structured around three distinct tiers of protection. Understanding these is the first step toward making an informed decision.
1. Civil Liability: The Legal Baseline
Often referred to as "Third-Party Insurance," this is the minimum legal requirement in most jurisdictions. Its scope is narrow: it covers only the damage you inflict upon others—whether that be bodily injury to pedestrians or other drivers, or property damage to third-party vehicles and infrastructure. It is critical to understand that this tier provides zero coverage for your own vehicle. If you are at fault, you must pay for your own repairs, which, given the complexity of modern automotive sensors and electronic components, can reach thousands of dollars in even minor accidents.
2. Extended Third-Party: The Balanced Approach
This middle-ground tier enriches the base liability coverage with specific, targeted protections. Most "Extended" or "Third-Party, Fire, and Theft" policies include coverage for common risks such as vehicle theft, fire damage, and shattered glass. It is a strategic compromise for those who want protection against external environmental risks without paying the premium associated with a full-coverage policy.
3. Comprehensive (All-Risks): The Gold Standard
The "All-Risks" or Comprehensive policy offers the most exhaustive protection. It covers damages to your own vehicle regardless of who is at fault, including single-vehicle accidents, vandalism, or weather-related damage. For anyone driving a new, financed, or luxury vehicle, this is rarely an optional luxury; it is a financial necessity to protect the significant capital invested in the car.
Factors Shaping Your Risk Profile: The Mathematics of Premiums
Insurance companies do not assign premiums randomly. They utilize complex actuarial models to determine the probability of a claim. Your personal profile is the primary input for these models.
The Impact of Driver History and Demographics
Your age, driving experience, and geographic location are the foundational pillars of your risk score. A young, inexperienced driver statistically poses a higher risk of accidents, which is why their premiums are traditionally higher. Conversely, a veteran driver with a clean history and a maximum "bonus" (no-claims discount) can access significantly lower rates, even for premium coverage.
The "Bonus-Malus" System: A Strategic Lever
The "bonus-malus" system—where your insurance rate fluctuates based on your history of accidents—is a critical mechanism to master. A stellar record acts as a financial asset, providing you with the leverage to purchase higher-tier coverage at a lower cost. Protecting this record should be a priority for every driver, as a single at-fault accident can lead to a "malus" that inflates premiums for years to come.
Vehicle Usage: Tailoring Coverage to Your Lifestyle
How you use your car is just as important as the car itself. An individual who only uses their vehicle for occasional weekend trips will naturally have a lower risk exposure than a commuter who spends two hours a day in heavy urban traffic. Professional usage, high-mileage commuting, or rural driving each present unique risk profiles. Aligning your policy with your actual usage—rather than a generic "average"—is one of the most effective ways to optimize your budget without sacrificing safety.
Chronology of a Claim: What Happens When the Unexpected Occurs
Understanding the lifecycle of an insurance claim is essential for knowing why certain coverage choices matter.
- The Incident: Immediate assessment of safety. At this point, the "Assistance" clauses of your contract become vital. Does your policy provide a towing service or a replacement vehicle?
- Reporting: Filing the report with the insurance provider. The accuracy of this report, often involving photographic evidence and witness statements, determines the speed of the settlement.
- Expert Assessment: An insurance adjuster evaluates the vehicle. If you have "All-Risks," this is where the quality of your policy is tested. Does it cover OEM (Original Equipment Manufacturer) parts, or is the insurer allowed to use salvaged components?
- Resolution: The payout or repair authorization. If you are underinsured, this is the stage where you discover you are responsible for the "gap" between the repair cost and your policy limit.
Supporting Data: Why "Hidden" Clauses Can Ruin You
While the premium price is what most consumers look at, the true cost of insurance is hidden in the fine print. According to industry data, the most common points of contention between insurers and policyholders involve:
- Deductibles (Franchises): A low premium is often offset by a high deductible. If you have a $1,000 deductible, you are effectively self-insuring for the first $1,000 of any accident.
- Exclusions: Many policies exclude specific scenarios, such as driving on unpaved roads, participation in track days, or even failing to secure your vehicle properly.
- Plafonds (Coverage Caps): Even a "comprehensive" policy may have a ceiling on the amount they will pay out for specific items like personal belongings left in the car or medical expenses for the driver.
Official Industry Perspectives: The Shift Toward Telematics
Industry experts and major insurance groups are currently emphasizing the rise of Telematics-based insurance. By installing a small device or using a smartphone app to monitor driving behavior (speeding, hard braking, time of day), insurers are moving away from broad demographic assumptions toward real-time behavioral data.
"The industry is moving toward a model of individual accountability," says an industry risk analyst. "Drivers who demonstrate consistent, safe behavior are increasingly being rewarded with personalized pricing that traditional models simply couldn’t offer." For the conscientious driver, this represents an opportunity to pay significantly less than the market average.
Implications for the Consumer: Building a Resilient Policy
How should a modern driver proceed? The answer lies in a disciplined, analytical approach to purchasing.
1. Perform a Needs Audit
Before looking at quotes, define your financial tolerance. If you were to lose your car tomorrow, could you afford to replace it? If the answer is no, you require comprehensive coverage. If you drive a vehicle with a low resale value, the cost of comprehensive coverage might actually exceed the value of the car itself.
2. Compare Beyond the Premium
Use online comparison tools to generate quotes, but do not stop there. Use these tools as a starting point to identify the range of providers. Once you have a shortlist, download the "General Conditions" document for each. Yes, it is dense, but it is where the truth about your protection resides.
3. Prioritize Essential Add-ons
Consider "Assistance from the first kilometer." Many people ignore this, only to find themselves stranded ten minutes from their home with no way to get their car to a shop. Similarly, legal protection insurance is often an inexpensive add-on that provides access to legal counsel in the event of a dispute—a vital safety net in a complex legal environment.
4. Review Annually
Your life changes, and so should your insurance. Have you moved? Did you change jobs? Did your annual mileage drop? Every significant life change should trigger a review of your policy. Insurers will rarely tell you if you are over-insured; it is your responsibility to ensure your policy reflects your current reality.
Conclusion: The Peace of Mind Dividend
The goal of auto insurance is not just to comply with the law, but to insulate your life from the volatility of the road. By moving past the superficial focus on monthly premiums and diving into the mechanics of coverage, deductibles, and individual risk profiles, you transform an annoying expense into a powerful tool for financial stability.
Whether you are a young driver purchasing your first policy or a seasoned professional looking to optimize your coverage, the principles remain the same: assess your risk, understand your limits, and prioritize the protections that matter most to your lifestyle. When you take the time to build a policy that fits your life like a glove, you aren’t just paying for an insurance card—you are buying the freedom to drive with total peace of mind.